Feeling better about money doesn't mean you're ready to buy.
You can feel better about your finances and still decide not to buy a home. Those aren't opposite positions.
The Bank of Canada's consumer survey released October 19 makes that distinction worth paying attention to. Respondents reported better financial health than in the previous quarter, but their spending plans weakened. High prices and economic uncertainty were still weighing on them.
Check when the answers were collected
The report is new. The interviews aren't from this week. The online survey ran from August 5 to 27, with follow up phone interviews from August 24 to September 4. Most online responses came before Canada and US trade talks broke down on August 21.
The Bank also notes that the improvements in reported financial health were measured before September's surge in bond yields. And these are consumers' opinions, not necessarily the Bank's own views.
That matters when a headline gets turned into a claim that buyers are coming back. This national survey isn't a count of GTA home purchases, and it doesn't tell us what someone will offer on a particular house. It isn't an interest rate decision either.
Confidence and a purchase are different things
Someone might feel more secure at work and still look at a home's carrying costs and decide the move can wait. Another household might need more space badly enough to move despite feeling nervous about the economy. Neither decision can be read out of a national mood survey.
For a buyer, put the home beside the life you would have after buying it. What happens to the money you normally save? Is there room for a repair? Would the commute cost more? Which expenses would you actually give up, and which ones are you only telling yourself you'll give up?
Don't answer with what you hope interest rates or home prices will do. Work from the property costs and financing terms you can verify now. Have your lender or licensed mortgage professional explain what applies to you before treating any borrowing amount as settled.
Sellers need evidence from their own market
A better confidence headline isn't a reason to add money to an asking price. Ask your Realtor to show you what similar homes have sold for, what buyers can choose instead and whether those competing homes are actually moving.
Keep those questions separate. A home can attract interest without attracting an acceptable offer. A national survey can't tell you whether your price, condition or presentation is the reason.
The survey is useful because it shows that feeling better and spending more don't automatically travel together. For your next move, the numbers attached to the actual home still have to work.
General real estate information. The buyer and seller considerations above are SirLuckHomes' interpretation, not findings or recommendations from the Bank of Canada.
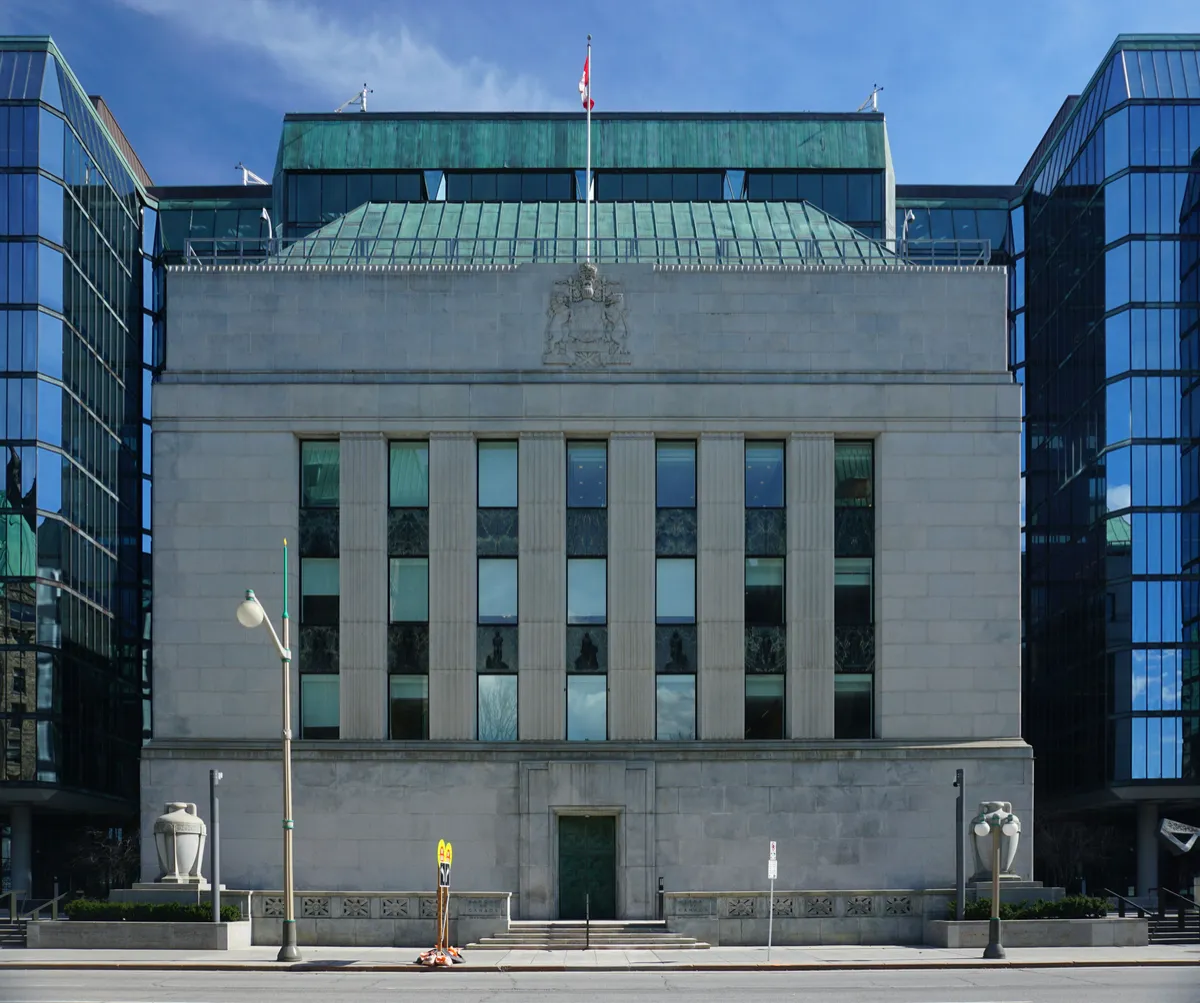
Archival photograph of the Bank of Canada in Ottawa, April 12, 2022, by 方畢可. Original photograph, used unchanged under CC0. No Bank endorsement is implied.
